
November 2023 Newsletter
Month of November Index Returns vs KIF:

Markets
Not just turkey and stuffing causing a sigh of relief from investors in the month of November.
Economic earnings were stronger than expected. Equity markets up strong.
Bond yields were down.
Oil prices declined.
Retail sales number showed consumers slowing.
Jobs report easing.
Labor productivity lower.
American credit card debt. 1.08 trillion. A new record.
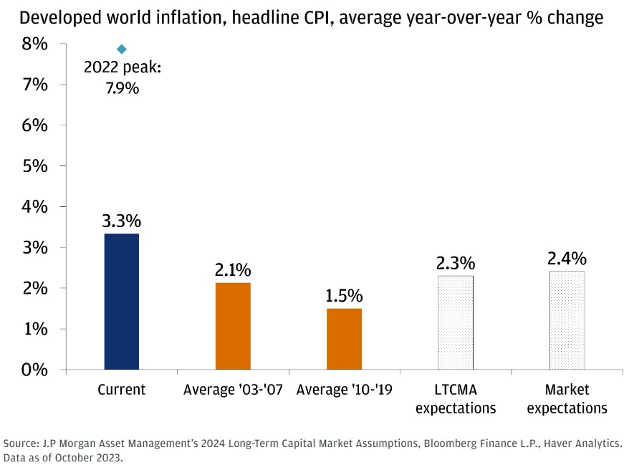
These continue to fuel the belief that the Federal Reserve will reduce rates next year, perhaps even sooner than most expect. The inflation rate in developed markets stood at 3.3%. This rate is the lowest since 2021 and is significantly below the highs of 2022. Nonetheless, it continues to exceed the level to which people have become accustomed over numerous years.
There are still issues we must face in 2024:
Two trillion in commercial debt that is coming due in 2025.
The persistence of the "work from home" trend, initiated by COVID, continues to adversely impact the office sector.
Increasing default rates seen in many debt sectors.
Geopolitical issues (wars).
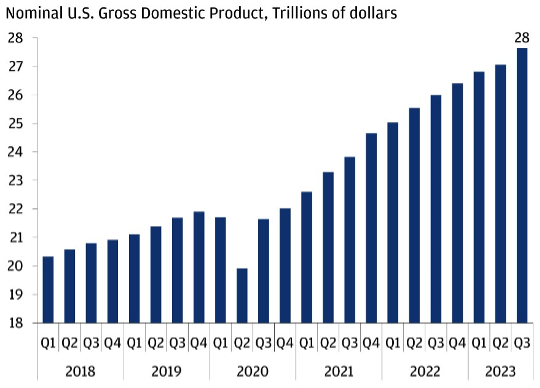
Despite the challenges that lie ahead, we embark on this journey from a robust foundation. The chart below, courtesy of JPM, exemplifies the resilience of the US GDP, further attesting to our strength.
We also think that these concerns will lead to restructuring possibilities for those with enough liquidity and a willingness to take on risk. Lower interest rates will also pave the way for many investors who are ready to invest the cash they've been hoarding. Private Credit Funds will keep gaining market share from banks and others who can't restructure these looming credit issues. We believe diligent investors will find many investment opportunities in the years to come. Specifically, they should keep their eyes on private markets. Both Private Debt and Private Equity are offering higher returns than their traditional market counterparts. However, there are still many risks out there, so make sure to do your due diligence and understand your risk exposure!
Kirkland Income Fund & Portfolio
November had good activity with three new loans being completed. We didn't recognize revenue from one loan because our ongoing assessment process lead us to believe there is a growing probability they may not pay next month. We're talking with the borrower to set up a cure. This way, the loan can catch up and hopefully return to a performing status. This conservative action is the main reason for this month's slight performance drop.
Confirmation of Thesis
Some investors in the Fund shared an article that discussed how a few folks from Goldman are building a new technology platform to take advantage of the opportunities in private debt. This platform is focused on lending to companies and not pursuing the space where we lend, but what was interesting is that they recognized what we realized years ago. There is an opportunity to help smaller businesses access private debt. There are also valuable opportunities for investors to access these smaller lending markets and capture excess returns. We wish them luck and we love when our thesis is supported by very smart folks.
Loan Activity Update
Frequently, as our Fund expands, inquiries arise regarding the sufficiency of loan demand. To put it succinctly, we are diligently striving to meet the unprecedented level of loan demand.
Over the recent months, the following number of loans have been submitted:
August: 39 loans submitted.
September: 40 loans submitted.
October: 48 loans submitted.
November: 39 loans submitted.
December: as of the 10th we have already had 16 new loans submitted.
We are seeing twice the number of loans compared to prior months. We're also witnessing an unprecedented number of loans clearing initial underwriting. In addition, we’ve also seen an increase in borrowers accepting our term sheets. However, as we've previously mentioned, it's crucial to remember that even if a borrower accepts a term sheet, they still need to go through our comprehensive due diligence process. This process scrutinizes not only the property but also the borrower.
Here's a brief look at our current pipeline.
Dillwyn VA $620k
Columbus OH $276k
Kansas City MO $840k
Ferndale MI $1.05M
Nashville TN $690k
Houston TX $500k
Florence KY $450k
Nashville GA $480k
Covington TN $339k
Milltown WI $155k
Micro-balance commercial real estate activity is very strong, and we are certainly seeing the demand. So, if you have cash to deploy, or your allocation to fixed income is out of balance with your target allocation, please schedule a call.
Making an Impact
“Investors feel good that while doing well, they are doing good…”
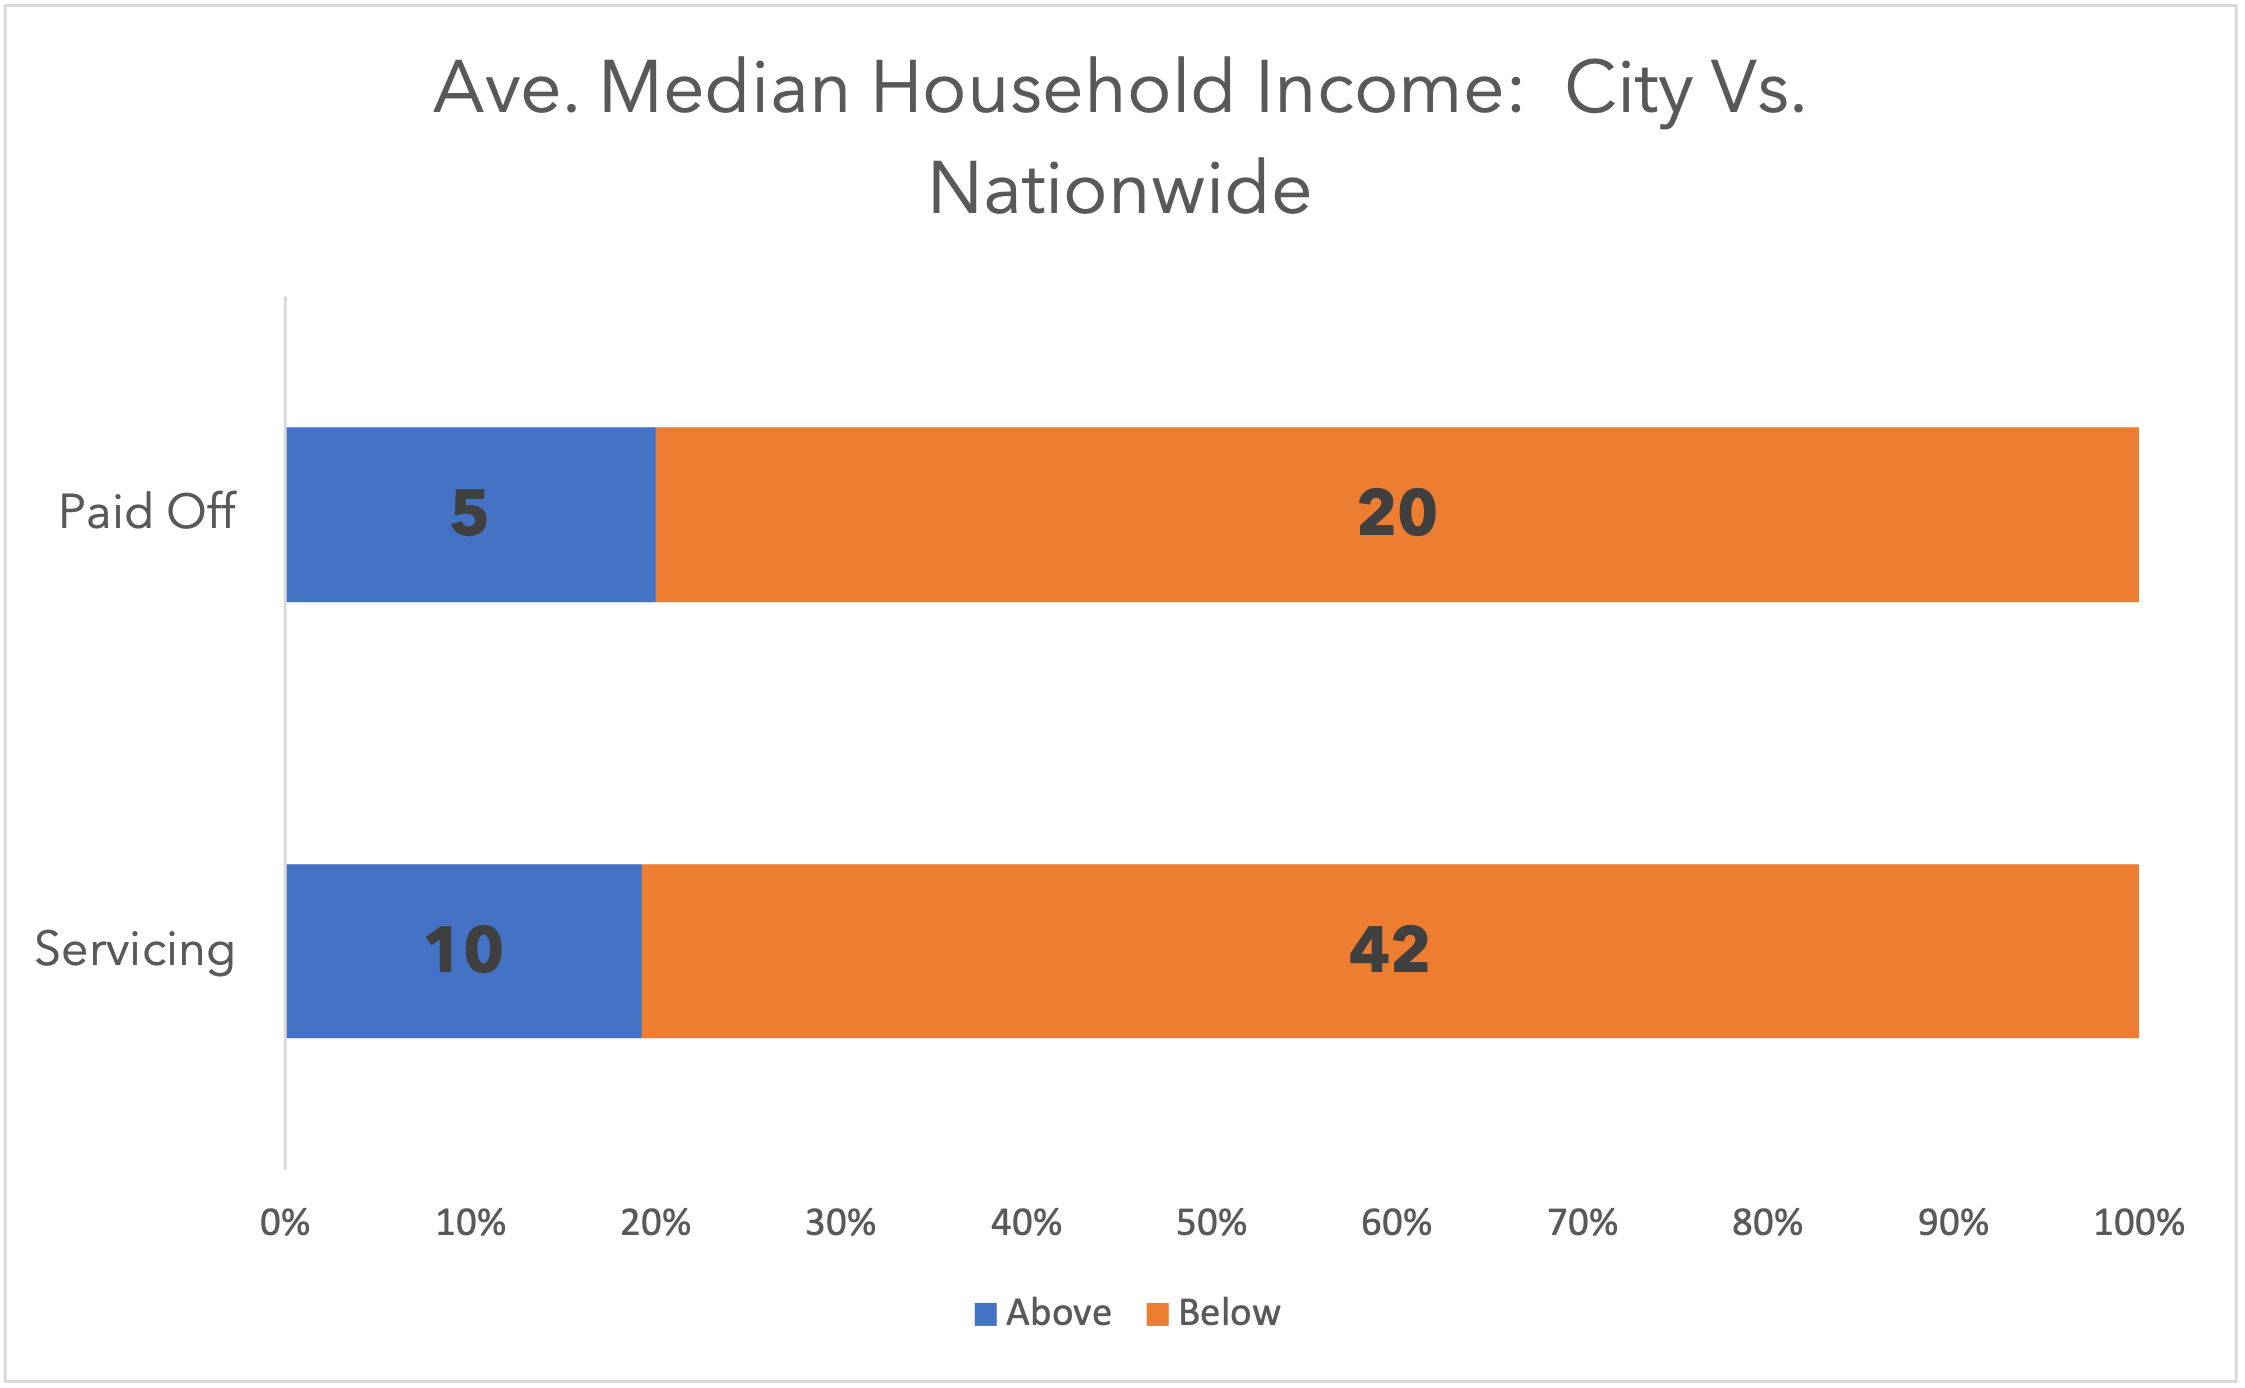
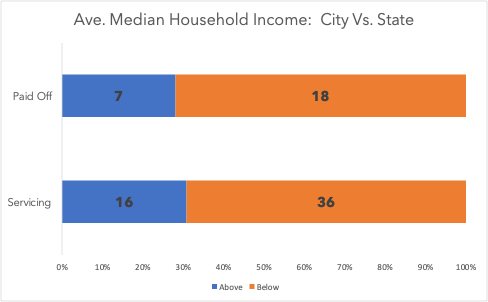
This statement has been a part of the Kirkland Income Fund description from the beginning. It originated from our funding opportunities and borrowers in geographic areas that are underserved. Brock and I love the fact that, albeit modest, we are having an impact. We now have sufficient data to quantify this impact. Kindly refer to the charts below:
Average Median Household Income
Borrower Ethnicity
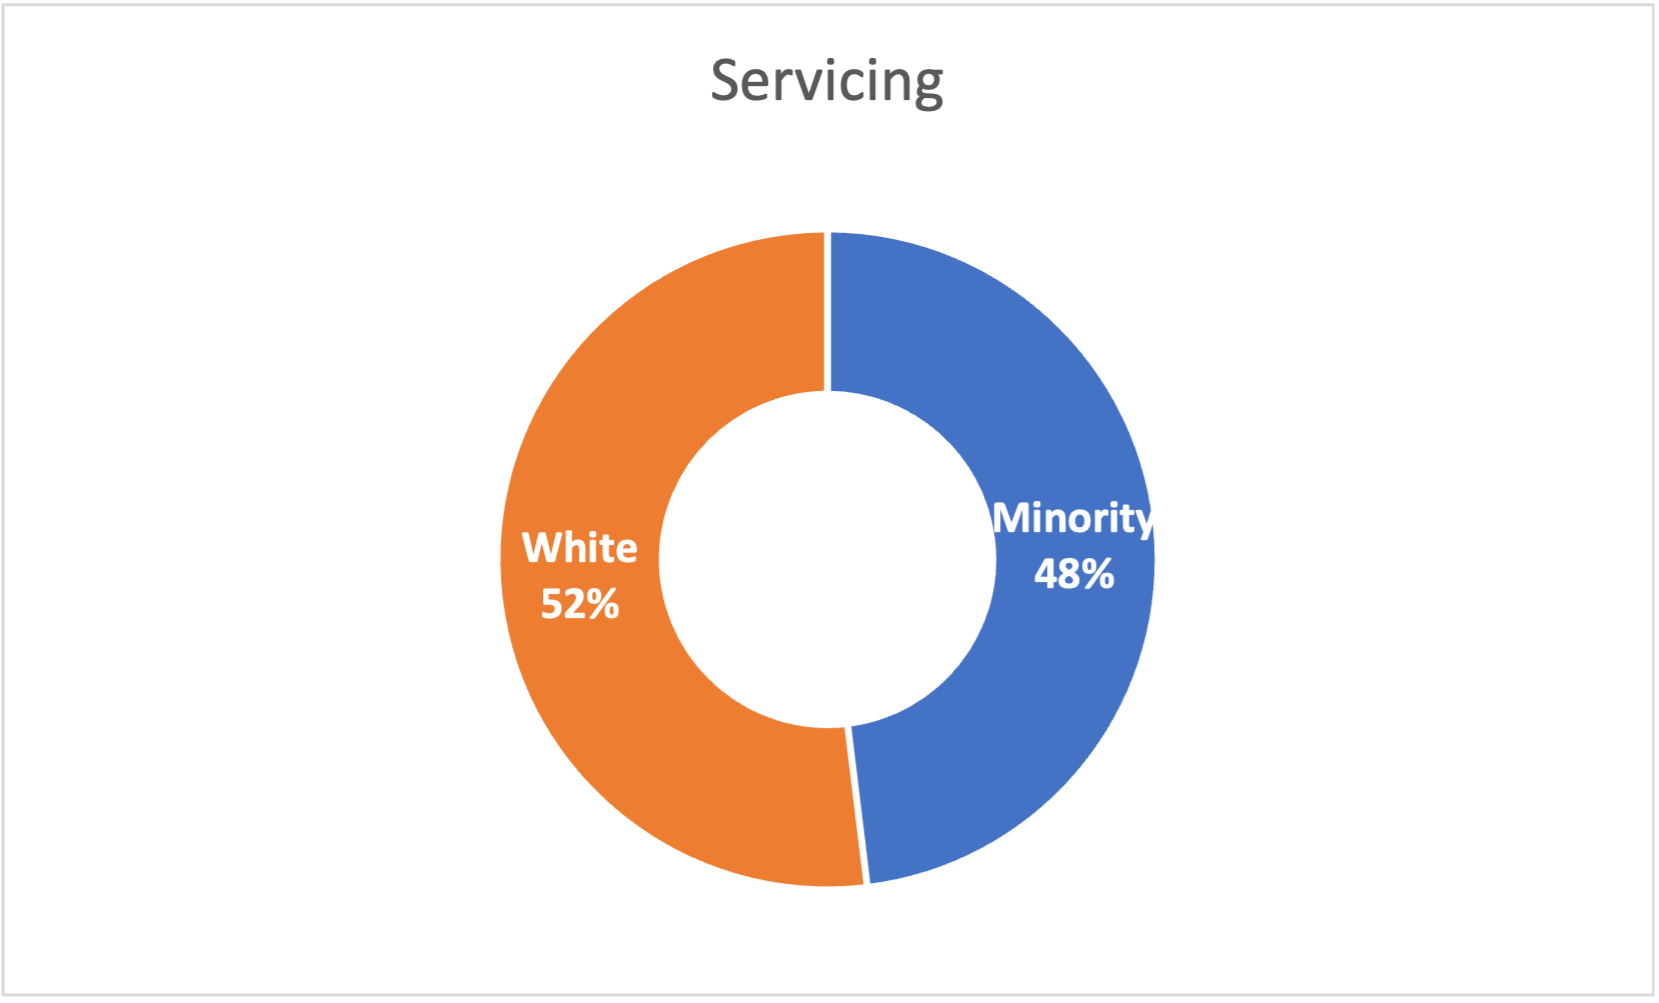
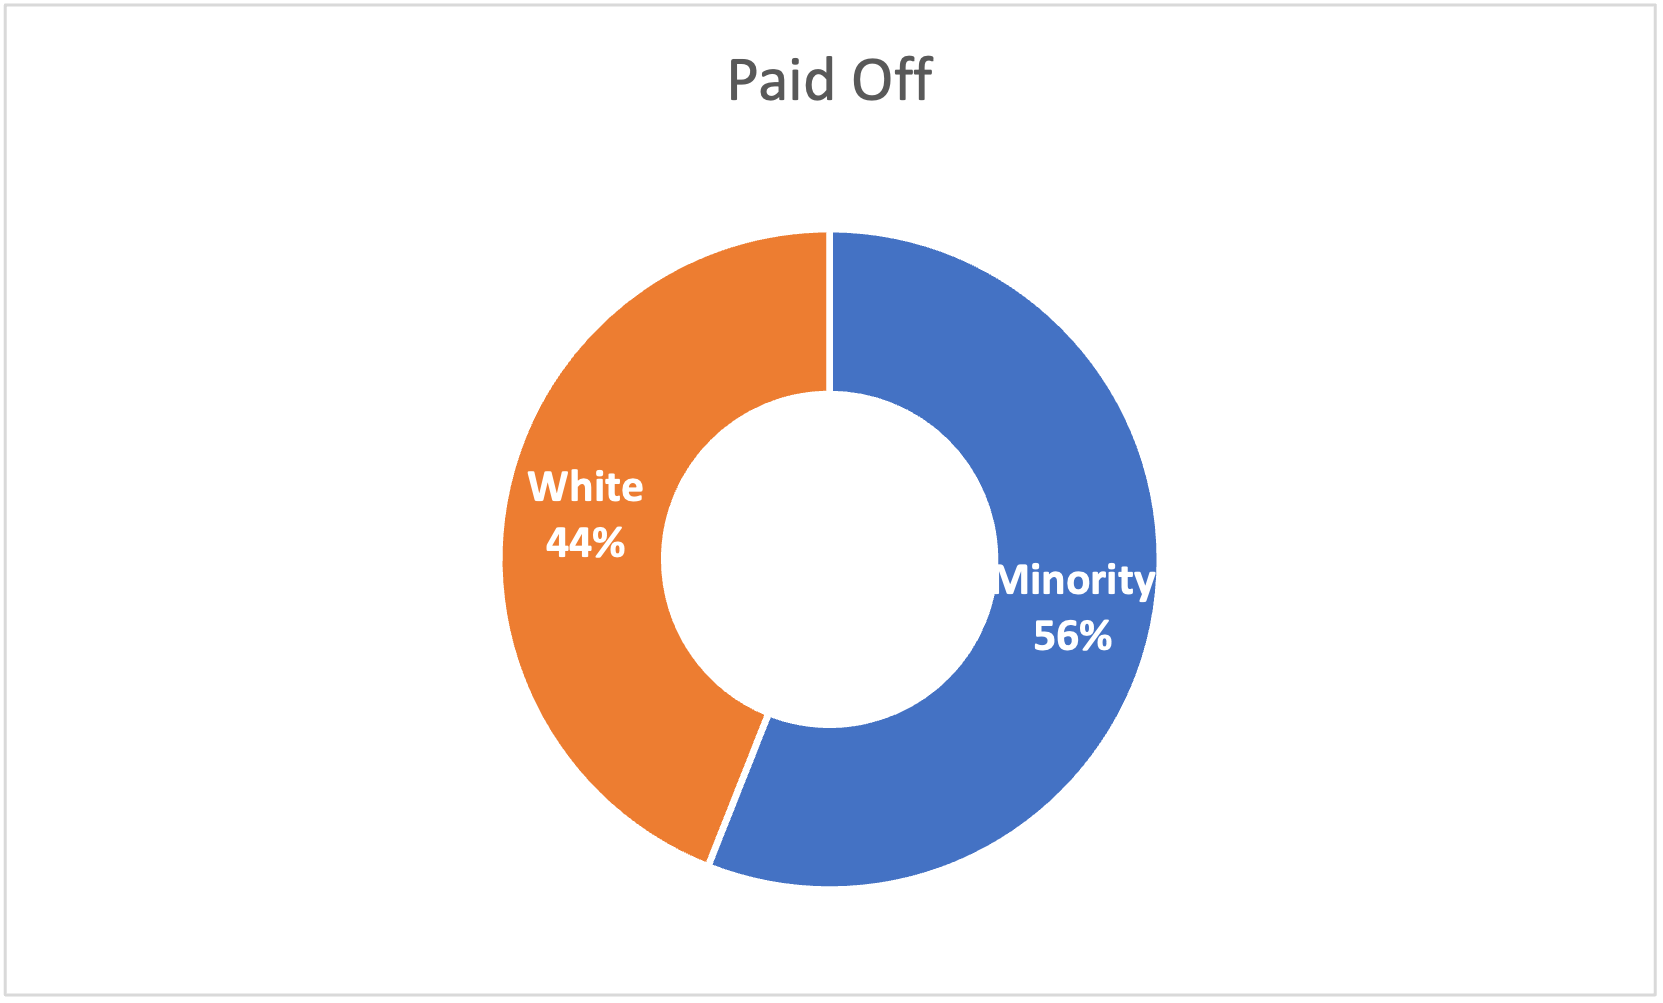
The data reveals that most of the properties are in cities where the average median household income is lower than the state or national average. We're also happy to report that many of our loans benefit minority borrowers.
Feedback from Investors
We recently conducted a survey among our investors to ascertain areas of interest. The results indicated that Private Debt and Due Diligence in alternative investments continue to be the primary focus. We have hosted many webinars addressing these subjects. Our plan for the forthcoming year includes the introduction of additional discussions. Should you wish to enhance your knowledge in these sectors, we invite you to visit our Investor Education page. If there are any areas of ambiguity, or if there is a specific topic you would like us to delve into, please do not hesitate to inform us. We can provide a more comprehensive coverage or schedule a call to cover the topic of your interest.
Have a great Holiday!
