
February 2024 Newsletter
Month of February Index Returns vs KIF:

Are we in a shift of the "Vintage" era?
Vintage Definition: The year and/or place where an item is made or produced.
In investments, "vintage" refers to a time period or specific year when investments were made. Some investment vintages are better than others, similar to how certain wines are preferred over others. A couple of examples are:
2005 to 2008 Vintage: The vintage of 2005 to 2008 was not a good time to invest because prices were high. We all remember what happened at the end of 2008. Many venture companies and long-only investors struggled during that period. Most portfolios performed poorly for several years, with some even suffering a 100% loss.
2009 to 2012 Vintage: The years 2009 to 2012 were a strong period for many investments. Valuations dropped significantly, and dispersion was prevalent in the public markets.
Are we in one of those time periods where the vintage is sour? Sometime in the future will we look back at the 2020 to 2024 vintage and cringe? Of course, there are always opportunities and money to be made in chaos, but overall, inflation, rising rates, and failing banks have been difficult for:
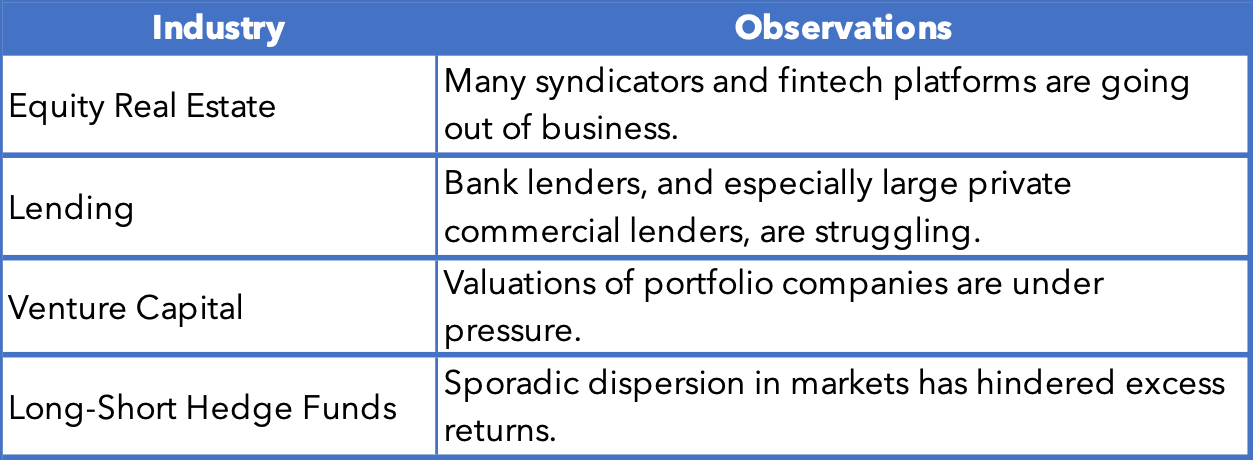
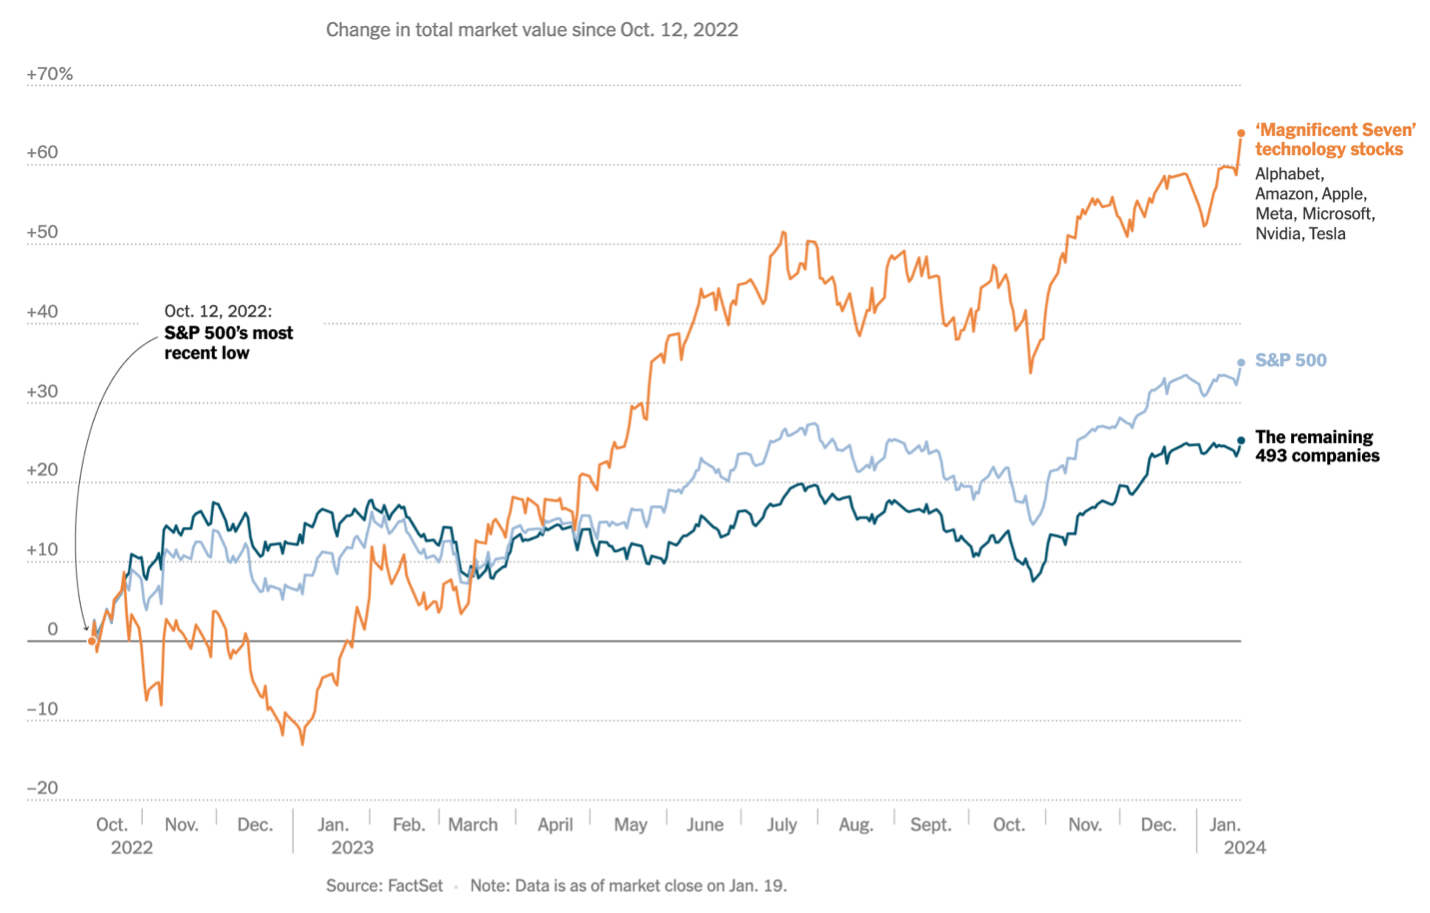
The public equity markets have seen a remarkable run. However, only a few companies are driving this growth. In the past, “The Four Horsemen” (Microsoft, Intel, Cisco, and Dell) dominated the markets. Now, a new group of leaders, known as “The Magnificent 7”, is spearheading the markets given the Artificial Intelligence era/hype. Times change constantly, and the question arises: "Who will be the next leaders?". Yet, it is challenging to find a financial advisor who is not perplexed by the current valuations.
S&P 500 TR rose by 5.34% in February and is up 7.02% YTD after a strong 2023. If you also worry about valuations, remember to diversify and look for investments that are not correlated to the majority of your portfolio holdings. The chart below clearly shows that most of the public companies in the index are not performing as well.
Usual Suspects:
Inflation: February saw prices increase by 0.4%. Inflation continues it stubborn stance.
Federal Reserve: With Inflation up in February, as predicted, the chances of seeing an earlier than expected ease in rates is doubtful. Higher rates for longer are what we can expect.
Banks: Continued bank problems. New York Community Bancorp announced they are looking to raise capital to shore up their balance sheet. We will certainly see more news like this as the year progresses. This is fueling an explosion of folks trying to get into Private Debt.
Geo-political: Peace talks are stalled and skirmishes breaking out again in the Middle East.
Kirkland Income Fund Updates:
I spoke with many of you about creating a distressed carve-out fund for the Kirkland Income Fund. We are pausing this plan for now because the current situation is uncertain and distressed debt is taking many twists and turns. Although we still believe in the idea, we will reconsider it later this year.
The February performance dipped slightly because some loans in the pipeline took longer to close. Borrowers are getting more cautious, which we appreciate. As previously mentioned, we expect some bumpiness in 2024. Some borrowers have faced operational difficulties and asked to make partial payments for a few months. We are being cautious and only recording the partial interest received, not the full amount owed. The borrowers will still need to pay the full accrued interest when the loan is repaid.
The Sub-REIT is now established, and we have submitted our first filing. Starting in April, the loans will be assigned, and we will start collecting and distributing interest from the REIT. I will keep you updated on REIT structures and the advantages it offers to the Kirkland Income Fund. If you have any questions, please schedule a meeting with me.
We are pleased to inform investors that we are ahead of schedule, and K1s were sent out last Friday. If you did not receive the email or are unable to access the K1 for any reason, please inform us so we can help you.
Brock and I have been working tirelessly with several candidates for a series of jobs available at Kirkland Capital Group. We are close to making final decisions and look forward to introducing some new faces as part of the Team.
